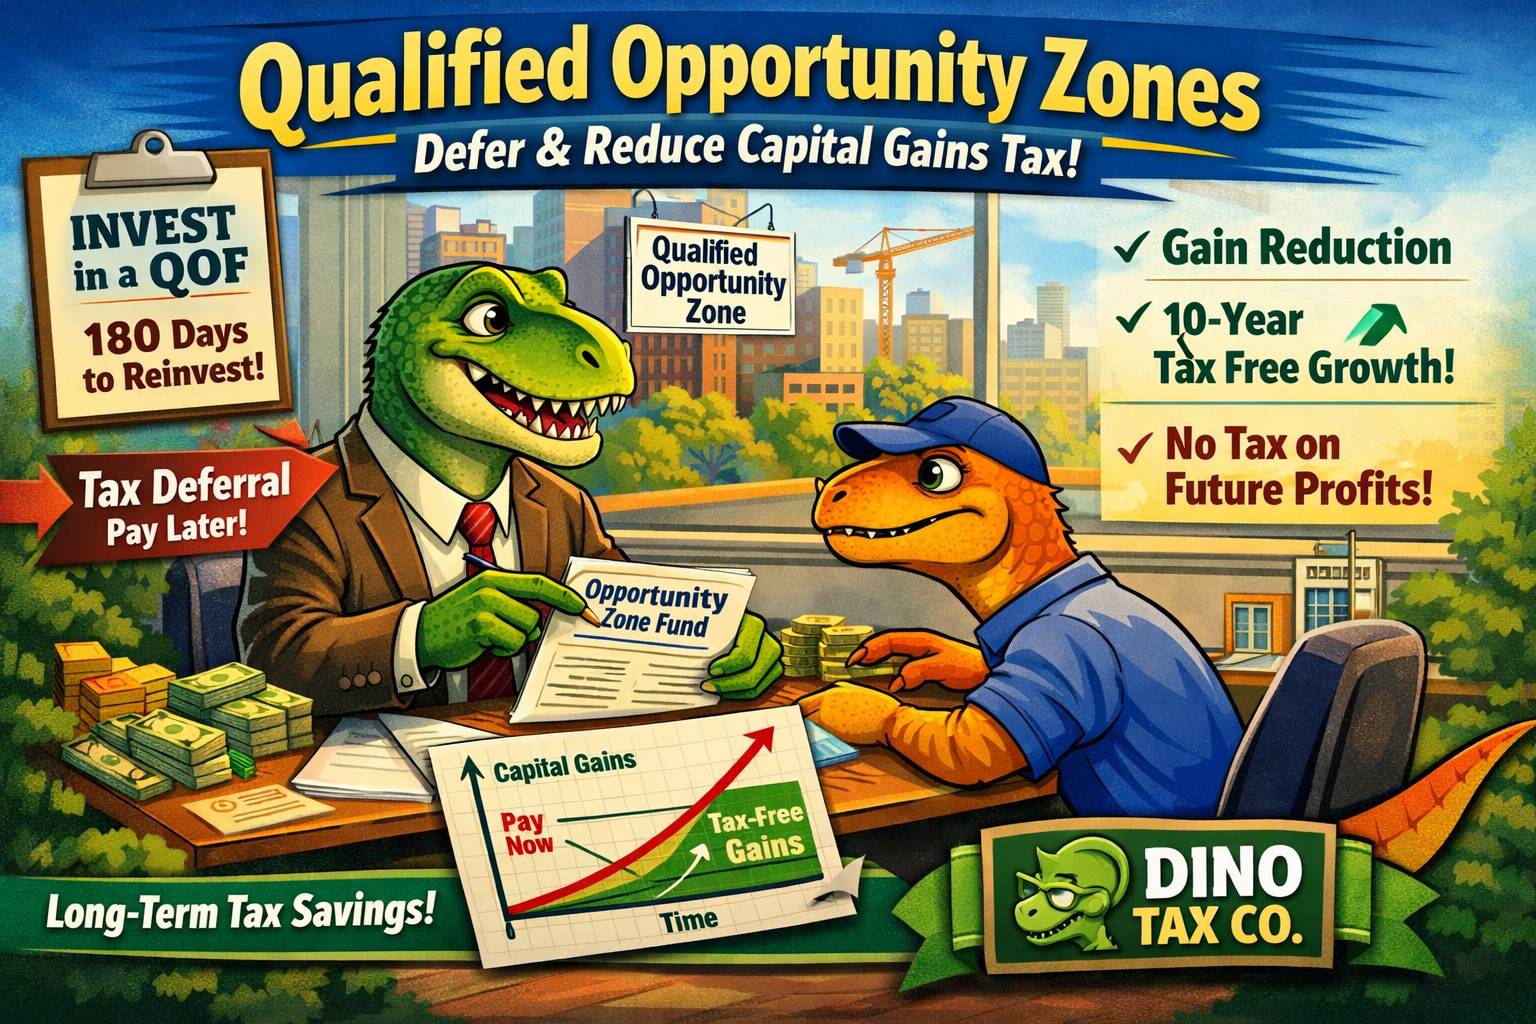
Many taxpayers are surprised to learn that the Internal Revenue Code offers powerful tax incentives for investing in economically distressed communities. These incentives operate through Qualified Opportunity Zones (QOZs) and Qualified Opportunity Funds (QOFs).
When used correctly, Opportunity Zone investments can allow taxpayers to:
- Defer capital gains taxes,
- Potentially reduce taxable gain, and
- Eliminate tax on future appreciation.
However, these benefits are tightly regulated. Failing to follow IRS rules can result in lost tax advantages and unexpected penalties.
This article explains how Opportunity Zones work, what the law requires, and how taxpayers can use them properly.
What Is a Qualified Opportunity Zone?
A Qualified Opportunity Zone is a low-income community designated by state governments and approved by the U.S. Treasury Department under Internal Revenue Code §1400Z-1.
These zones were created by the Tax Cuts and Jobs Act of 2017 (TCJA) to encourage private investment in struggling areas.
Once an area is designated, investors may obtain special tax treatment by placing capital into qualifying projects located within that zone.
What Is a Qualified Opportunity Fund (QOF)?
A Qualified Opportunity Fund is an investment vehicle formed for the purpose of investing in Opportunity Zone property.
Under IRC §1400Z-2(d)(1), a QOF must:
“Hold at least 90 percent of its assets in qualified opportunity zone property.”
Most QOFs are structured as:
- Partnerships, or
- Corporations taxed as partnerships.
The fund must self-certify with the IRS by filing Form 8996 each year.
Which Capital Gains Are Eligible?
Only capital gains are eligible for Opportunity Zone deferral.
Under IRC §1400Z-2(a)(1)(A), taxpayers may elect to defer:
“Gain from the sale or exchange of any property to an unrelated person.”
Key requirements include:
- The gain must be recognized for federal tax purposes,
- The sale must be to an unrelated party, and
- The gain must be reinvested within 180 days.
Eligible gains include:
- Stock sales
- Real estate sales
- Business asset sales
- Cryptocurrency gains
- Partnership gains
Ordinary income does not qualify.
The 180-Day Reinvestment Rule
Taxpayers must reinvest their capital gain into a QOF within 180 days of the sale.
Treasury Regulation §1.1400Z2(a)-1(b)(2) provides:
“The 180-day investment period begins on the date on which gain would be recognized.”
For partnerships and pass-through entities, special timing rules may apply.
Missing the deadline eliminates all Opportunity Zone benefits.
Tax Deferral Benefits
When a taxpayer properly reinvests eligible gain, the IRS allows deferral of tax.
Under IRC §1400Z-2(a)(2)(B):
“The taxpayer may elect to defer recognition of such gain until the earlier of—
(i) the date the investment is sold, or
(ii) December 31, 2026.”
This means:
- No capital gains tax is paid now,
- Taxes are postponed until 2026 or earlier disposition.
This deferral alone can create major cash-flow advantages.
Basis Adjustments and Gain Reduction
Earlier versions of the law allowed basis step-ups at 5 and 7 years. Those benefits have largely expired. However, basis rules still matter.
Under IRC §1400Z-2(b)(2)(B):
“The basis of such investment shall be increased by 10 percent of the deferred gain” (for qualifying holdings).
Although most step-up windows have closed, careful planning may still preserve partial benefits in limited cases.
The 10-Year Exclusion: The Biggest Opportunity Zone Benefit
The most valuable tax advantage applies to long-term investors.
If a taxpayer holds a QOF investment for at least 10 years, future appreciation may be tax-free.
Under IRC §1400Z-2(c):
“The basis…shall be equal to its fair market value on the date of sale.”
This means:
- Deferred gain is taxed in 2026, but
- All post-investment growth may be excluded.
For successful projects, this can eliminate millions in future capital gains.
Qualified Opportunity Zone Property Requirements
To qualify, investments must meet strict asset rules.
Treasury Regulation §1.1400Z2(d)-1(d) requires that QOF property be:
- Qualified Opportunity Zone Stock
- Qualified Opportunity Zone Partnership Interests, or
- Qualified Opportunity Zone Business Property
Additionally:
- Property must be acquired after December 31, 2017
- Original use must begin in the zone, or
- Property must be substantially improved
“Substantial improvement” generally requires doubling the building’s adjusted basis within 30 months.
90% Asset Test and Penalties
QOFs must satisfy the 90% asset test.
Under IRC §1400Z-2(d)(1):
“At least 90 percent of the assets of such fund shall be qualified opportunity zone property.”
Failure triggers monthly penalties under IRC §1400Z-2(f).
Improper fund management can eliminate investor benefits.
Common Opportunity Zone Mistakes
Many taxpayers lose benefits due to avoidable errors:
1. Missing the 180-Day Deadline
Late reinvestment permanently disqualifies the gain.
2. Using Ineligible Funds
Only capital gains qualify.
3. Poor Fund Compliance
If the QOF fails testing, investors suffer.
4. Improper Property Development
Failure to substantially improve property disqualifies assets.
5. Early Exit
Selling before 10 years forfeits the exclusion benefit.
Are Opportunity Zones Right for Everyone?
Opportunity Zone investments are not passive tax shelters. They involve:
- Real estate risk
- Business risk
- Liquidity limits
- Regulatory complexity
They are best suited for:
- High-income taxpayers
- Real estate investors
- Business owners with large asset sales
- Crypto and stock investors with major gains
They are usually not appropriate for short-term investors.
Planning Tips for Taxpayers
Before using Opportunity Zones, consider:
✔ Confirm gain eligibility
✔ Track the 180-day period
✔ Review QOF compliance history
✔ Examine development plans
✔ Coordinate with tax counsel
A poorly structured investment can create more tax problems than it solves.
Conclusion: Opportunity Zones Can Be Powerful — If Done Correctly
Qualified Opportunity Zones remain one of the most significant capital gains incentives in the tax code.
When structured properly, they can:
- Defer current taxes,
- Improve cash flow, and
- Eliminate future appreciation tax.
But strict rules apply. Professional guidance is essential before committing funds.
If you are considering an Opportunity Zone investment, consult with a qualified tax attorney or CPA to ensure full compliance with federal law.
At Dino Tax Co, we help clients navigate tax matters ranging from unfiled returns to IRS letters and levies and everything in between with clarity and confidence. If you’d like guidance on your situation, schedule a consultation today. Call or text (713) 397-4678 or email davie@dinotaxco.com. We’re here to help you take the next step.

Leave A Comment