Most taxpayers understand that wages are taxable.
Business profits are taxable. Interest and dividends are generally taxable. Rental income can be taxable. Even prizes, gambling winnings, and bartering transactions can create federal income tax consequences.
But what happens when the money itself comes from illegal activity?
Can the federal government really require someone to pay income tax on money obtained through theft, bribery, kickbacks, or another unlawful activity?
Surprisingly, the answer is generally yes.
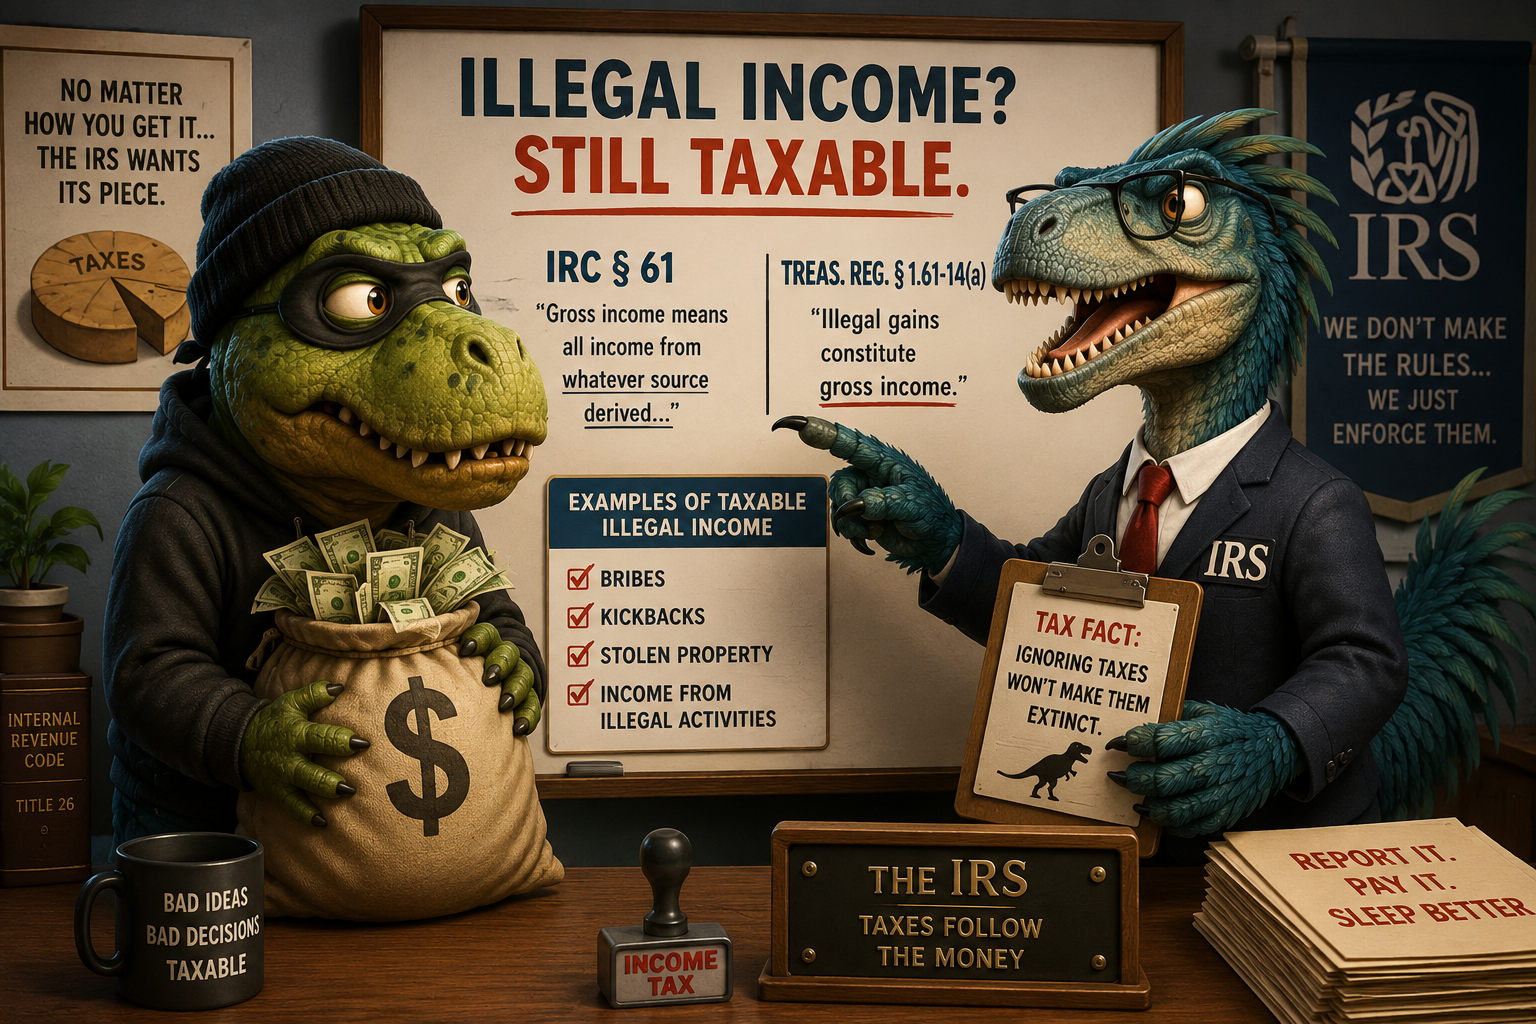
Federal income tax law does not ordinarily ask whether income was earned legally before deciding whether it is income. Internal Revenue Code § 61 broadly defines gross income as “all income from whatever source derived” unless another provision of federal tax law provides an exclusion.
The Treasury Regulations make the rule even more explicit.
Illegal gains constitute gross income.
That creates one of the stranger features of federal tax law: a person can potentially violate one law by obtaining money and create a separate tax problem by failing to report that same money.
IRC § 61 Uses an Extremely Broad Definition of Income
The starting point is IRC § 61(a).
Section 61 provides that, unless the Internal Revenue Code says otherwise:
“gross income means all income from whatever source derived”
The statute then lists familiar examples, including compensation for services, business income, gains from property, interest, rents, royalties, dividends, annuities, pensions, and income from the discharge of indebtedness.
But that list is not exhaustive.
The words “from whatever source derived” are deliberately broad.
Nothing in the general definition says that the source must be lawful.
That distinction becomes explicit in the Treasury Regulations.
The Treasury Regulations Specifically Say Illegal Gains Are Income
Treasury Regulation § 1.61-14 addresses miscellaneous items of gross income.
The regulation states:
“Illegal gains constitute gross income.”
That is an unusually short and direct tax rule.
The same regulation illustrates just how broad the federal concept of income can be. It also provides that certain punitive damages are gross income, that another person’s payment of a taxpayer’s income taxes can constitute gross income unless otherwise excluded, and that treasure trove can constitute gross income when reduced to undisputed possession.
The legality of the underlying transaction therefore does not by itself determine whether an economic gain falls within gross income.
A taxpayer generally cannot defend the failure to report income simply by arguing that the taxpayer was never legally entitled to receive it.
Bribes Are Generally Taxable to the Person Receiving Them
The IRS expressly instructs taxpayers that bribes are income.
Suppose a person secretly receives $20,000 in exchange for improperly influencing a business decision.
The payment may violate federal or state law.
But the illegality of the transaction does not ordinarily make the $20,000 disappear for federal income tax purposes.
The recipient may have received an economic benefit over which the recipient exercises control.
Accordingly, the payment can constitute gross income.
This creates two conceptually separate legal issues.
The first is whether receiving the bribe violated some criminal, civil, licensing, or regulatory law.
The second is whether the money received constitutes taxable income under federal tax law.
The answer to the second question can be yes even when the answer to the first question is also yes.
Kickbacks and Side Payments Can Also Be Taxable
The same general principle applies to kickbacks.
The IRS specifically identifies kickbacks, side commissions, “push money,” and similar payments as income that generally must be reported.
Consider a salesperson who secretly receives payments from a supplier for steering customers toward that supplier.
Or imagine an employee who receives an undisclosed payment from a vendor in exchange for directing the employer’s purchases to that vendor.
Whether those arrangements are illegal will depend on the circumstances and applicable law.
But calling the payment a kickback rather than a commission does not ordinarily prevent it from being income.
For federal income tax purposes, the important question is generally whether the taxpayer received an economic gain that is not excluded from gross income.
Stolen Property Can Be Taxable Too
Perhaps the most surprising application involves theft.
Current IRS guidance states that if a taxpayer steals property, the taxpayer generally must report the property’s fair market value as income in the year of the theft unless the property is returned to its rightful owner during that same year.
That rule can sound bizarre at first.
A thief does not acquire good legal title merely because federal tax law treats the stolen property as income.
Tax law is addressing a different question.
The tax system is determining whether the taxpayer obtained an economic benefit sufficiently under the taxpayer’s control to constitute income.
Property law and criminal law may simultaneously require the property to be returned and impose other consequences.
Federal income tax treatment does not legalize the underlying conduct.
Illegal Businesses Can Generate Taxable Income
The rule extends beyond isolated bribes or thefts.
Income generated through an illegal business or ongoing illegal activity can also constitute taxable income.
Treasury Regulation § 1.61-14 does not distinguish between lawful and unlawful gains when it states:
“Illegal gains constitute gross income.”
The IRS likewise instructs taxpayers that income from illegal activities must be included in income.
That means a person cannot ordinarily avoid federal income tax merely because the business producing the money violates another law.
This principle also helps explain why tax prosecutions have historically been useful against people engaged in criminal enterprises.
Even when proving the underlying source of every dollar presents difficulties, substantial unreported income can create its own federal tax consequences.
But Can Someone Deduct the Cost of Paying a Bribe?
Here federal tax law draws another important distinction.
Receiving illegal income can produce taxable gross income.
Paying certain illegal expenses, however, does not necessarily produce a business deduction.
IRC § 162 generally permits deductions for ordinary and necessary expenses paid or incurred in carrying on a trade or business.
Congress has nevertheless placed important limitations on that general rule.
Treasury Regulation § 1.162-18 contains detailed rules concerning illegal bribes and kickbacks.
For certain payments to government officials or employees, the regulation provides:
“No deduction shall be allowed under section 162(a)”
when the requirements of the rule are satisfied.
In other words, calling an illegal payment a “business expense” does not necessarily make it deductible.
The Regulations Even Give an Example
Treasury Regulation § 1.162-18 contains a particularly useful illustration.
In the regulatory example, a corporation selling hospital equipment employs a state Superintendent of Hospitals for the purpose of obtaining an improper advantage in making sales to hospitals over which the superintendent has authority.
The corporation pays the superintendent $5,000.
Because the payment is illegal under applicable state law, the regulation concludes that IRC § 162(c)(1) prevents the corporation from deducting the payment as a trade or business expense.
The example illustrates an important asymmetry in federal tax law.
The recipient can have taxable income from an unlawful payment while the person making the payment may simultaneously be denied a deduction for making it.
The tax system does not have to treat both sides of an illegal transaction symmetrically.
Other Illegal Bribes and Kickbacks Can Also Be Nondeductible
Treasury Regulation § 1.162-18(b) extends the deduction limitation beyond certain payments to government officials.
The regulation generally provides:
“No deduction shall be allowed under section 162(a)”
for certain payments that constitute illegal bribes, illegal kickbacks, or other illegal payments under federal law or under generally enforced state law when the statutory and regulatory requirements are satisfied.
The regulation specifically explains that, for purposes of this rule:
“a kickback includes a payment in consideration of the referral of a client, patient, or customer.”
That language can matter in industries in which referral payments, commissions, or similar arrangements are heavily regulated.
Simply characterizing a payment as a marketing expense, referral fee, consulting payment, or commission does not necessarily determine its federal tax treatment.
The underlying nature of the payment matters.
Medicare and Medicaid Kickbacks Receive Special Treatment
The regulation contains an additional rule involving federal health care programs.
Treasury Regulation § 1.162-18(c) provides that no deduction is allowed under § 162(a) for certain kickbacks, rebates, or bribes connected with items or services paid for under Medicare, Medicaid, or other covered federal programs.
Notably, the regulation states that this rule can apply to a covered kickback, rebate, or bribe “whether or not illegal.”
This is an important reminder that tax deductibility and criminal legality are separate questions.
An expenditure does not necessarily become deductible merely because no criminal prosecution occurs.
Paying Tax Does Not Make Illegal Conduct Legal
There is an equally important misconception to avoid.
Reporting illegal income on a federal income tax return does not legalize the underlying conduct.
Tax law merely determines whether an economic gain must be included in gross income.
Criminal law, property law, professional licensing law, employment law, health care law, and other legal systems may impose entirely separate obligations or penalties.
Someone who steals $50,000 does not acquire lawful ownership of the money merely by reporting $50,000 of income.
Likewise, someone who receives a prohibited kickback does not transform the payment into a lawful transaction by paying federal income tax on it.
The tax obligation exists alongside whatever other legal consequences apply.
What If the Illegal Property Is Returned?
Timing can become especially important when property is wrongfully obtained and later returned.
Current IRS guidance provides a particularly clear rule for stolen property: its fair market value generally must be reported in income in the year it is stolen unless it is returned to the rightful owner in that same year.
Returning property in a later tax year can create more complicated tax issues.
Federal tax law contains doctrines dealing with situations in which a taxpayer includes an amount in income in one year and later becomes obligated to repay it.
The correct treatment can depend heavily on the particular facts, the amount involved, the taxpayer’s accounting method, and the legal circumstances surrounding the repayment.
Taxpayers dealing with substantial repayments should therefore avoid assuming that they can simply amend an earlier return or deduct the repayment without analyzing the applicable rules.
The IRS Does Not Need a Form 1099 to Make Income Taxable
Another important principle applies here.
Taxability generally does not depend on whether the taxpayer receives an information return.
A bribe does not become tax-free because nobody issued a Form 1099.
Neither does a secret kickback.
The basic federal income tax question is whether the taxpayer received gross income—not whether someone else reported the transaction to the IRS.
Information-reporting forms can help the IRS detect income, but they do not generally create the underlying tax liability.
Why Does the Tax Code Work This Way?
At first glance, taxing illegal income may seem strange.
But the alternative would be considerably stranger.
If illegal gains were categorically excluded from gross income, federal tax law would effectively give unlawful economic activity a tax advantage over lawful work.
A worker earning $80,000 legally would owe federal income tax.
Someone obtaining $80,000 through illegal activity could potentially claim that the same economic gain was exempt precisely because obtaining it was unlawful.
IRC § 61 avoids that result by beginning with an extraordinarily broad definition of gross income.
The Treasury Regulations then remove any lingering ambiguity:
“Illegal gains constitute gross income.”
The Bottom Line
Federal income tax law generally does not require income to come from a lawful source before it can be taxable.
IRC § 61 broadly includes “all income from whatever source derived,” and Treasury Regulation § 1.61-14 expressly provides that illegal gains constitute gross income.
As a result, bribes, kickbacks, income from illegal activities, and even stolen property can create federal income tax consequences.
At the same time, federal tax law may deny deductions for certain illegal payments. Treasury Regulation § 1.162-18 contains detailed restrictions involving illegal bribes, kickbacks, payments to government officials, and certain payments associated with federally funded health care.
The result is a deliberately unforgiving system:
Illegal income can still be taxable, while the expense of generating or facilitating that income may not necessarily be deductible.
For taxpayers confronting unusual sources of income, repayment obligations, kickbacks, restitution, or other legally disputed payments, the exact federal tax consequences can depend heavily on the facts and timing involved.
At Dino Tax Co, we help clients navigate tax matters ranging from unfiled returns to IRS letters and levies and everything in between with clarity and confidence. If you’d like guidance on your situation, schedule a consultation today. Call or text (713) 397-4678 or email davie@dinotaxco.com. We’re here to help you take the next step.

Leave A Comment