One of the most misunderstood concepts in federal income taxation is when income is considered received. Many taxpayers assume that income is only taxable when cash physically hits their bank account. That assumption is wrong—and it can lead to unexpected tax bills, penalties, and IRS disputes.
The doctrine that governs this issue is called constructive receipt, and it plays a major role in cash-basis taxation, independent contractor income, bonuses, commissions, escrowed funds, deferred payments, and even online platform earnings.
The Constructive Receipt Rule Explained
Most individual taxpayers use the cash method of accounting, meaning income is reported when received and expenses are deducted when paid. But “received” doesn’t always mean “in hand.”
Under Treasury Regulation § 1.451-2(a):
“Income although not actually reduced to a taxpayer’s possession is constructively received by him in the taxable year during which it is credited to his account, set apart for him, or otherwise made available so that he may draw upon it at any time…”
The regulation continues with the critical limitation:
“…however, income is not constructively received if the taxpayer’s control of its receipt is subject to substantial limitations or restrictions.”
This single sentence drives thousands of audits every year.
Why the IRS Cares About Constructive Receipt
The IRS uses constructive receipt to prevent taxpayers from artificially delaying income simply by refusing to take possession of money that is already available to them.
If income is:
- Available to you
- Under your control
- Not subject to real restrictions
Then it is likely taxable now, not later.
Common Real-World Examples
1. Bonuses and Year-End Payments
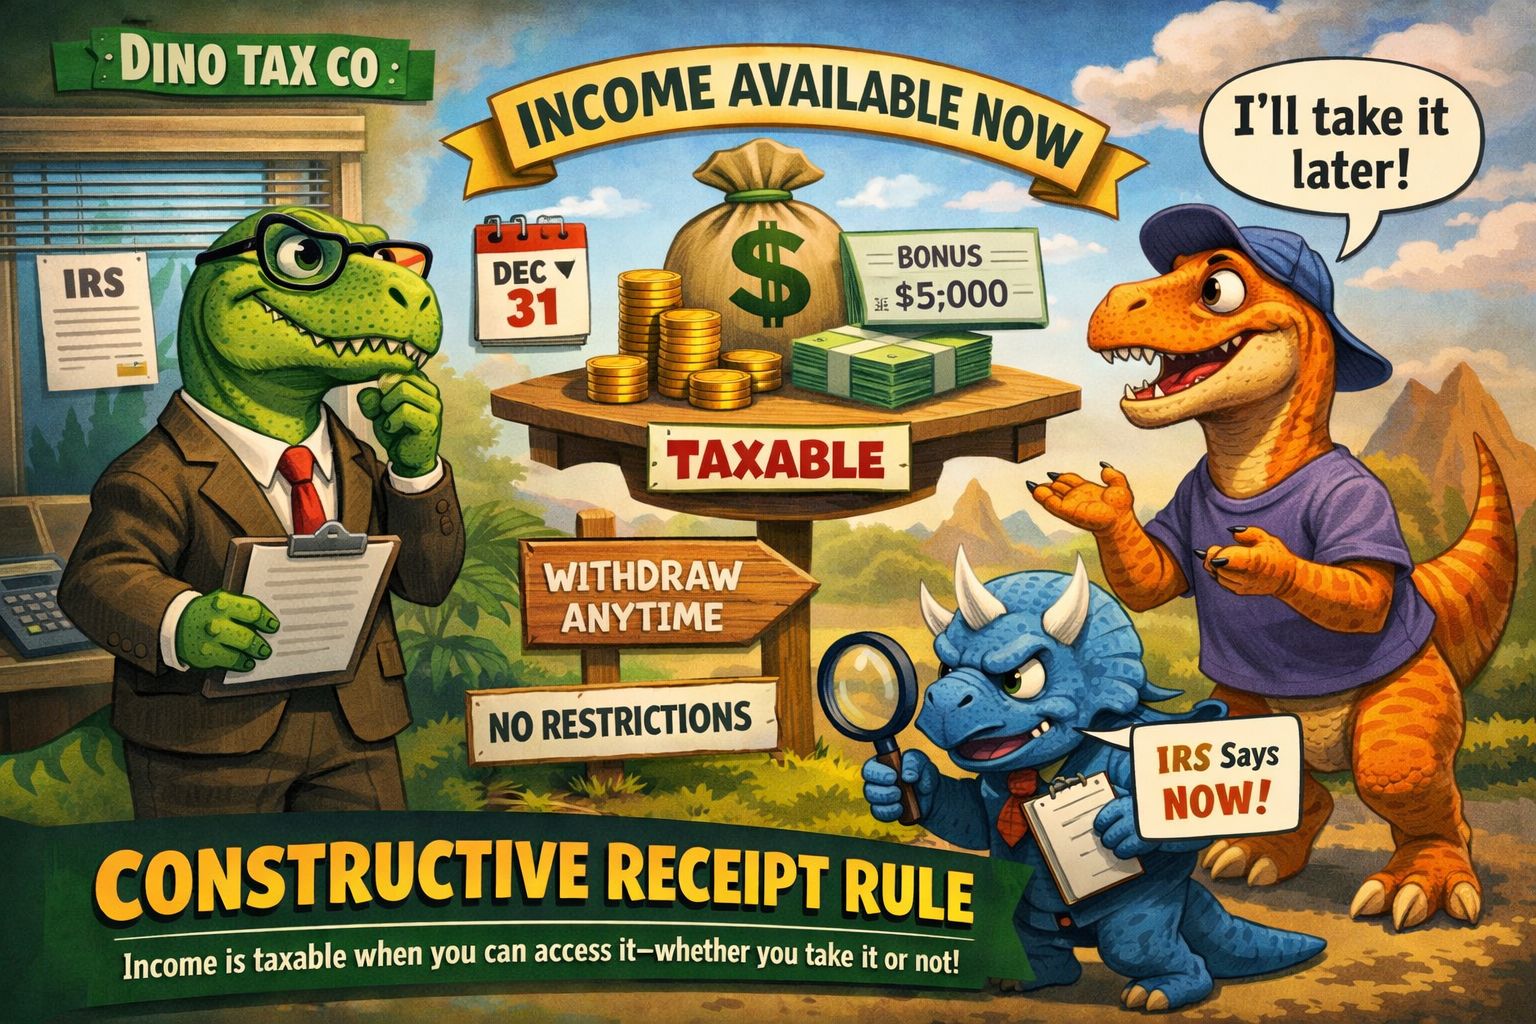
If an employer makes a bonus available on December 31, but you ask them to pay it in January, the IRS may still treat it as current-year income if you had the ability to take it earlier.
2. Independent Contractors and Online Platforms
If a payment is credited to your account on a platform (such as a freelance marketplace or payment processor), and you can withdraw it at any time, the IRS may treat that as constructive receipt—even if you leave it sitting there.
3. Escrow and Restricted Funds
Funds held in escrow are not constructively received if you cannot access them due to a legitimate contractual restriction. This is where the “substantial limitation” language becomes critical.
4. Deferred Compensation
True deferred compensation arrangements must meet strict requirements. Simply “choosing” not to take income does not automatically defer tax.
What Counts as a “Substantial Limitation”?
The IRS looks at actual control, not labels.
Examples of substantial limitations include:
- Contractual prohibitions on withdrawal
- Legal restrictions
- Third-party control over funds
- Conditions precedent that have not yet occurred
Mere inconvenience, delay, or personal choice does not qualify.
Statutory Authority Behind the Rule
The constructive receipt doctrine is grounded in IRC § 451(a), which provides:
“The amount of any item of gross income shall be included in the gross income for the taxable year in which received by the taxpayer…”
Treasury Regulations then define what “received” means in practice—expanding it well beyond physical possession.
Why This Matters for Audits and Penalties
Misunderstanding constructive receipt can lead to:
- Underreported income
- Accuracy-related penalties under IRC § 6662
- Interest on late-paid tax
- Disputes over timing rather than amount (the hardest kind to win)
This issue comes up frequently in audits involving:
- Cash businesses
- Consultants
- Professionals
- Gig workers
- Closely held business owners
Key Takeaway
If money is available to you without real restriction, the IRS may treat it as taxable—even if you didn’t touch it.
Timing matters. Control matters. Documentation matters.
If you’re unsure whether income is constructively received, that uncertainty alone is a sign you should get professional advice before filing.
At Dino Tax Co, we help clients navigate tax matters ranging from unfiled returns to IRS letters and levies and everything in between with clarity and confidence. If you’d like guidance on your situation, schedule a consultation today. Call or text (713) 397-4678 or email davie@dinotaxco.com. We’re here to help you take the next step.

Leave A Comment